Car insurance, the North-South divide that remains: after the tax, the real issue is understanding why insurance costs so much more in Naples
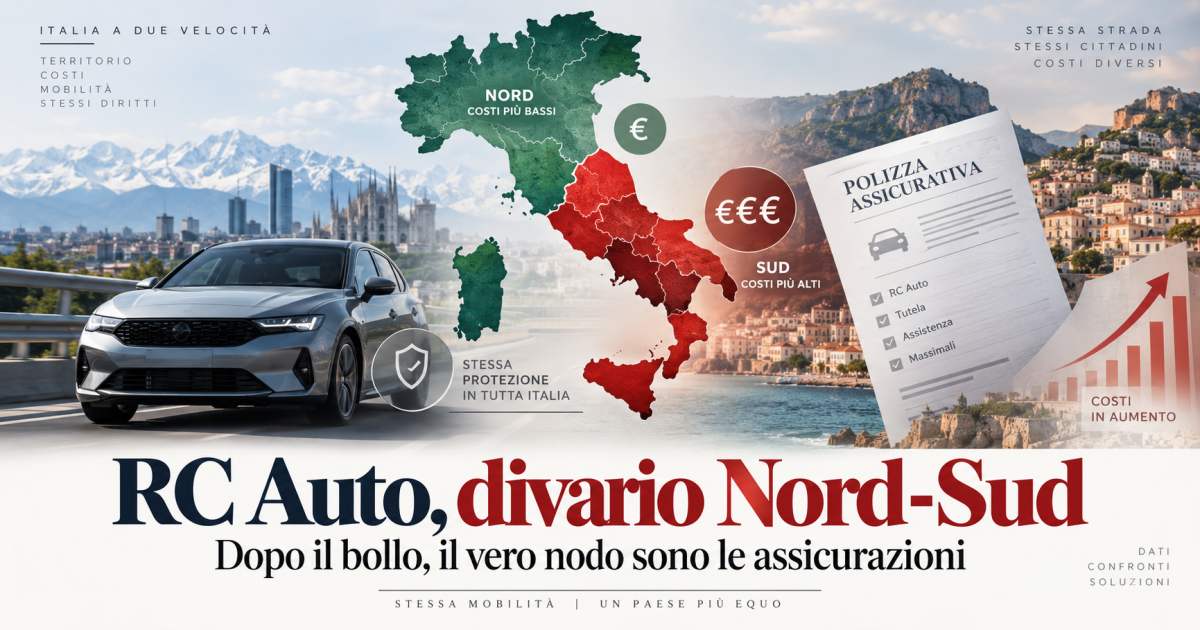
In the photo, a representative element of the story.
Following the announcement of a road tax exemption for 2027, perhaps it's time to address one of the most obvious imbalances affecting Italian motorists: insurance. Southern Italy continues to pay significantly more than other parts of the country. Insurance companies report claims, costs, and fraud, but the data reveal a more complex reality. And behind the economic problem, another, profoundly political one emerges: Southern Italy contributes millions of votes to national majorities, but how effectively does it convert those votes into representation of its interests?
The Government has announced a 2027 exemption from road tax on first vehicles up to 80 kW, with no ISEE limits.
According to the Ministry of Infrastructure and Transport, the potential target group includes 24.608.867 people . The government's stated goal is to subsequently make the measure structural.
A measure that will obviously please millions of families.
When politicians manage to leave a few hundred euros in citizens' pockets, keeping public finances sustainable, it's difficult to view it negatively.
But the announcement about the stamp duty inevitably raises another question.
Because after the road tax, perhaps we should also address car insurance.
And here we enter one of the most evident and persistent territorial imbalances in our country.
Insurance does not cost the same throughout Italy
It's not a feeling.
It's not the usual complaint of the southern citizen.
It's a fact.
The latest available IVASS IPER survey concerns the first quarter of 2026 and was published on July 14, 2026. The survey measures the prices actually paid by Italian policyholders for motor vehicle liability insurance.
And territorial differences continue to be important.
For years, Naples has been one of the provinces where insuring a car costs significantly more than in many northern provinces.
Here the question inevitably arises.
Why?
The generally accepted answer is well known: in areas where there are more accidents, more expensive compensation, greater litigation, or a higher risk of fraud, companies must protect themselves and therefore increase premiums.
As an economic principle, it makes perfect sense.
If insuring a certain population costs more, it is understandable that the premium may be higher.
But how much of that difference is actually explained by risk?
And this is where it gets interesting.
Do many more accidents really happen in the South?
One of the beliefs that risks taking root in public debate is that insurance policies cost much more in the South simply because there are many more accidents there.
But road safety data reveal a decidedly more complex Italy.
In 2025 in Italy there were 177.207 road accidents resulting in injuries , with 237.822 injured and 2.868 victims.
Accidents increased by 2,2% compared to 2024, while fatalities decreased by 5,3%.
This means first of all a very simple thing:
Accidents are certainly not a peculiarity of the South.
They happen in the North, in the Center and in the South.
And when we look at the territorial distribution of road fatalities, a reality emerges that does not at all coincide with the idea of a substantially virtuous North as opposed to a South where all the accidents occur.
Already in 2024, the mortality rate per 100 inhabitants was 3,9 in the North-West, 5,9 in the North-East, 5,5 in the Centre, 5,4 in the South and 5,5 in the Islands.
The North-East, therefore, even had a higher rate than the South.
Of course, this doesn't mean that car insurance should cost more in Veneto or Emilia-Romagna than in Campania.
However, this means that using the generic word “accidents” to explain every tariff difference risks being misleading.
Road accidents and insurance claims are different things
However, a fundamental distinction must be made.
The accidents counted by ISTAT do not coincide with all the claims considered by insurance companies.
The ISTAT data concern road accidents resulting in personal injuries recorded by the authorities.
Companies also have to deal with claims involving only material damage, repair costs, personal injury, litigation, compensation claims, and anti-fraud activities.
Istat itself recalls that, in addition to the over 18 billion euros of social cost of accidents resulting in injuries recorded in 2025, ANIA estimates approximately 4,4 billion euros in costs relating to accidents with damage to property alone.
We cannot therefore simply take the number of accidents and turn it into an insurance rate.
But we can ask for greater transparency.
And above all, we can ask ourselves whether the difference in premiums is entirely justified by risk factors.
IVASS: Technical factors explain 55% of provincial differences
And this is probably one of the most interesting facts of the whole issue.
In its report on its activities in 2025, published in June 2026, IVASS analyzed the territorial differences in motor vehicle insurance premiums.
The result deserves attention.
According to the Institute, the main technical indicators analyzed can explain approximately 55% of the differences observed between provinces.
Therefore, there remains a residual component linked to factors not observed in the model.
IVASS identifies claims frequency as the most important factor: a 1% increase in claims frequency is associated, in the model used, with a 0,42% increase in the average premium.
The average cost of claims also has an impact: a 1% increase in the average cost is associated with a 0,32% increase in the premium.
However, the relationship observed with the percentage of claims investigated for suspected fraud is much more modest: a 1% increase in this indicator is associated with a 0,05% increase in the average premium, holding the other variables considered constant.
This is an important fact because it allows us to move away from slogans.
Fraud exists, but it can't explain everything.
Of course, insurance fraud exists.
To deny it would be absurd.
There are fake accidents, inflated compensation claims, false testimonies, and organized criminal schemes surrounding compensation.
And it is right that companies, the judiciary and supervisory authorities fight them.
But the IVASS numbers themselves suggest that the problem of territorial tariffs cannot be reduced simply to the sentence:
"There are more scams in the South, so everyone pays more."
The formation of the prize is much more complex.
They include the frequency and cost of claims, litigation, management of disputed claims, anti-fraud activities and other elements.
And IVASS itself notes that these factors, in the model analyzed, explain a significant portion but not the entire territorial difference.
And it is precisely in the space that remains that a legitimate question arises.
The question: is the South also paying to keep other markets lower?
And here we come to the doubt.
It must be stated clearly: there is no evidence in the public data we examined to support the claim that airlines deliberately increase fares in the South to keep those in the North lower.
To claim this as fact would be incorrect.
But the doubt can be raised.
Because an insurance company operates in a national market, develops complex pricing policies, competes in different provinces, and must maintain an overall economic balance.
It is therefore legitimate to ask how much of the territorial differences depends exclusively on risk and how much may also depend on the commercial strategies adopted by individual companies.
We are not claiming that there is some sort of “hidden tax” paid by the South to finance the North.
We're asking for something much simpler:
If a citizen pays 200, 300, or even more euros than another citizen with similar characteristics, it would be useful to know very clearly where that difference comes from.
Voice by voice.
Euro for euro.
Why should a citizen who has never had an accident have to pay?
Then there is a question that any motorist immediately understands.
Let's imagine a citizen of Naples.
He has been driving for twenty years.
It does not cause accidents.
He has never submitted a fraudulent claim.
Maintains a good merit rating.
Respect the rules.
Yet part of its reward inevitably continues to depend on the territory in which it lives.
In essence, he pays not only for himself, but also for the statistical risk associated with the territorial community to which he belongs.
From an insurance perspective, this is understandable: the entire insurance system works through risk sharing and classification.
But politically and socially it remains a huge question.
Because if that classification produces very significant differences, the risk is that residence will become a sort of permanent economic penalty.
Same car, same license, same state
And this is the point that should interest politics.
Two Italian citizens.
Same car.
Same merit class.
Same age.
Same insurance history.
Same license.
But different provinces.
Is it acceptable that place of residence can make a significant difference in price?
Some difference is probably inevitable.
Demanding the same tariff throughout Italy while ignoring any risk factor would be equally irrational.
But the problem is not to establish that there should be no difference.
The problem is understanding how proportionate it is.
After the road tax, it would be time to talk about car insurance too.
And that's why the announcement about the stamp duty could represent an opportunity.
If politicians consider the cost of cars a sufficiently important problem to intervene in the road tax, then perhaps they should also open a serious discussion on car insurance.
Not necessarily by imposing prices.
But by increasing transparency and competition.
Forcing us to make territorial criteria more easily understandable.
By periodically checking how much of the provincial differences is actually explained by risk.
Placing more value on the insured's individual history than simply on geographical location.
Because the virtuous citizen should be valued more and more for what he does , and less and less for what other citizens who live near him might statistically do.
Then there is another problem: the South votes
And from here the reflection inevitably becomes political.
Why the South votes.
Of course he votes.
The South elects deputies and senators, contributes to the composition of Parliament, and can have a very important influence in the formation of national majorities.
Therefore, it would be incorrect to say that the South has no representatives in the institutions.
He has them.
The problem is probably something else.
Does being elected in the South really mean representing the South?
And this is where one of the great paradoxes of Italian politics arises.
The South can elect a government without being able to impose its own problems
Millions of votes from the South could contribute to the victory of a coalition.
Entire southern regions can hand over dozens of parliamentary constituencies to a party or an alliance.
Those votes can contribute substantially to the creation of a majority.
But then comes the time to govern.
And that's where representation should really be measured.
Because political representation isn't just about counting how many MPs were born in Naples, Bari, Palermo, or Reggio Calabria.
It's who decides that matters.
It matters who sets the national agenda.
It matters who controls the political structures of the parties.
What counts is whoever manages to transform a local problem into a national priority.
It's up to you who can say:
On this issue, the South cannot continue to be penalized.
Being Southern is not enough to represent the South
This is a key point.
A member of parliament born in Naples does not automatically represent the interests of Campania.
A minister born in Sicily does not automatically mean that the government has a favorable policy towards Sicily.
A person's geographical origin and the political representation of a territory are two different things.
It is possible to have many parliamentarians elected in the South and simultaneously have a limited capacity on the territory to transform those presences into a common political strategy on the major economic issues of the South.
And it is probably here that the feeling that many citizens of the South feel arises.
We're here when it's time to vote. But are we equally here when it's time to decide?
The power rooms are not just the Parliament
When we talk about power, in fact, we are not only talking about the seats of the Chamber of Deputies and the Senate.
Real decisions are built across a much broader network.
Party leadership.
Ministries.
Parliamentary committees.
Technical structures.
Large public companies.
Economic organizations.
Authority.
Financial centers.
Production system.
Industrial relations.
Capacity for territorial pressure.
It is this network that determines how much impact a territory can actually have.
And this is what the South should probably ask itself.
Not only:
How many parliamentarians have we elected?
But:
What weight do they have when it comes to decisions?
The South is also responsible
However, it would be too convenient to attribute all this only to the North.
Because there is inevitably also a Southern responsibility.
If the South elects dozens and dozens of parliamentarians, then those parliamentarians must also be held accountable.
Where am I when it comes to insurance costs?
Where am I when it comes to infrastructure discussions?
Where are they when transportation is inadequate?
Where are they when a Southern company starts with higher logistics costs?
Where are they when local healthcare produces such profound differences?
The point cannot always and only be:
«the North penalizes us».
You also need to ask:
"Who did we send to represent us and what is he doing?"
A strong territory should not limit itself to protesting
A truly strong territorial representation should demand data.
For example on insurance.
How many accidents are actually reported province by province?
What is the average cost?
What is the frequency?
What percentage of requests are considered suspicious?
How much does the litigation weigh?
How much do thefts cost?
How much do personal injuries cost?
How much do all these factors really affect the final price?
And especially:
How much of the difference remains after considering them?
IVASS has already taken an important step by demonstrating that the technical indicators analyzed explain approximately 55% of the provincial differences examined by the model.
The task of politics should be to go even deeper.
The South is not short of votes
Because maybe that's the point.
The South is not short of votes.
It is not politically irrelevant when the polls open.
The problem is what happens next.
The votes are collected.
Members of Parliament are elected.
Governments are formed.
But then some imbalances remain for decades.
And this phenomenon cannot be attributed to a single government.
The problem of North-South differences cuts across center-right and center-left executives, technical governments, and majorities of very different natures.
The parties are changing.
The Prime Ministers are changing.
The ministers change.
Some problems remain.
And it is perhaps precisely this continuity that should give us pause for thought more than any of the day's controversies.
The real doubt does not only concern insurance
In the end, therefore, the problem of car insurance becomes almost a symbol.
The initial doubt remains.
Is it possible that some of the higher tariffs in the South contribute indirectly to the overall trade balance of the companies?
The available data do not allow us to affirm this.
But they certainly allow us to ask for greater transparency.
And above all, they allow us to ask a much bigger political question.
Why does a territory with millions of votes so often continue to feel it matters much less when it comes to distributing resources, opportunities, and costs?
The South votes, but must demand to be represented
This is perhaps the final point.
There is no need for wars between North and South.
There is no point in imagining an evil North versus a victim South.
We need data.
Responsibility.
Transparency.
And true political representation.
Because if a Southern citizen pays more insurance, he must know why.
If that difference is fully justified by the numbers, those numbers must be shown.
If, however, there are components that insurance risk cannot fully explain, policy must have the courage to delve deeper into them.
But above all, the South should stop considering the simple fact of electing someone sufficient.
The South votes.
The South contributes to electing majorities and governments.
The South has a numerically significant parliamentary representation.
But the real question comes the day after the elections:
Who really represents the South when entering the rooms where decisions are made?
Because a territory is not politically strong when it can only elect a government.
It is strong when it manages to ensure that, once that government is elected, its problems also become problems for the entire country.
And perhaps the auto insurance gap would be a good place to start.
Breaking News
Villarreal-Napoli, Allegri thunders: "We can't concede goals like this."
Massimiliano Allegri gives Napoli no concessions after the heavy 3-1 defeat at… Read more
Napoli loses in the Champions League, but Politano doesn't shy away: "I made the game difficult, and I apologize."
Matteo Politano isn't looking for excuses after Napoli's 3-1 defeat to Villarreal. In the… Read more
Fuel prices and traffic in Naples mean taxi drivers return to the Prefecture: "Concrete answers are needed."
Naples - Fuel prices and city traffic are once again at the center of institutional debate with the… Read more
Phlegraean Fields, taxes and mortgages suspended. Musumeci: "One billion euros for the next ten years."
Rome - A long-term strategic plan that focuses on prevention rather than… Read more
SuperEnalotto: No 6s in the October 13nd draw, jackpot at €40,3 million
Superenalotto, here's the winning combination: 4 - 21 - 30 - 33 - 38 - 78 Jolly Number:… Read more
10eLotto Winning Numbers for Today, October 13, 2026
In this evening's 10elotto draw, the following numbers were drawn: 01 – 03 –… Read more
National Newspaper
Registration No. 1301 of 2016 – ROC 030531
Director: Giuseppe Del Gaudio
To contact the editorial staff click HERE |
Download our Official ANDROID APP
